
SBA Line Maximums
Program Specifics
Eligibility and Guarantees
Online Lender Caps
Revenue-Based Limits
Asset-Based Lending
Approval Factors
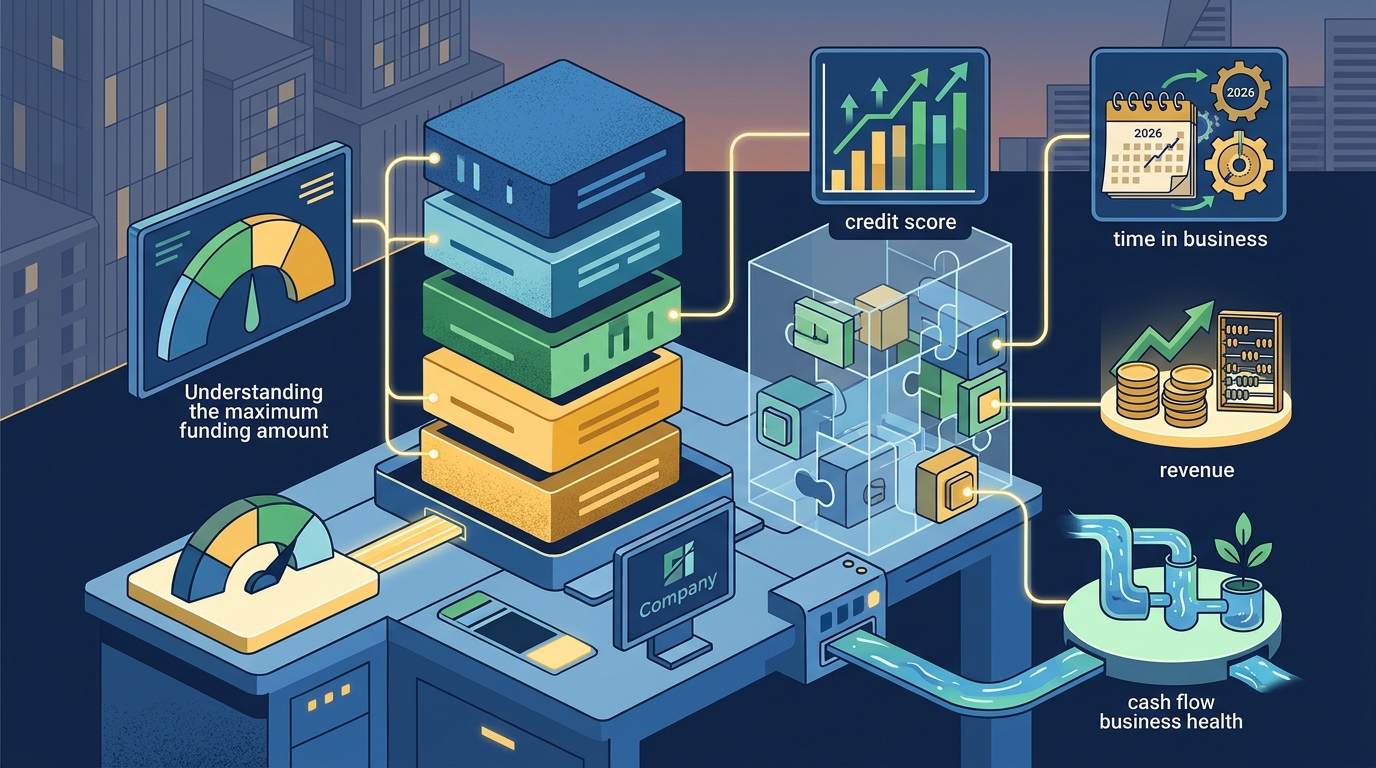
Understanding the maximum funding amount is only half the equation. The other half is determining whether you will qualify for that maximum. Approval for a business line of credit depends on several key factors. These factors vary by lender but generally include credit score, time in business, revenue, and cash flow. A higher credit score and longer time in business can increase the likelihood of qualifying for a higher limit.
Credit Score and History
Personal and business credit scores play a significant role in determining the credit limit. Most online lenders require a personal credit score of at least 650 to 700 for their standard products. However, some lenders consider bad credit or lower credit scores, especially if the business has strong revenue. A credit score is a numerical representation of a borrower's creditworthiness. It is calculated based on payment history, credit utilization, length of credit history, and new credit inquiries. A higher score indicates lower risk to the lender, which can result in a higher credit limit and better terms.
Time in Business and Revenue
Most lenders require that the business has been operating for at least 6 to 12 months. Some lenders may require 2 years of operation for larger limits. Revenue is another critical factor. Lenders look at both gross revenue and net profit. A business with high revenue but low profit may not qualify for a large credit line. Lenders also look at the consistency of revenue. A business with stable, predictable revenue is more likely to qualify for a higher limit than a business with volatile revenue.
Cash Flow and Debt Service
Cash flow is the lifeblood of any business. Lenders analyze cash flow to determine the business's ability to make debt payments. A business with strong positive cash flow is more likely to qualify for a higher credit limit. Lenders also look at the debt service coverage ratio (DSCR). The DSCR is a financial ratio that measures a business's ability to service its debt. A DSCR of 1.25 or higher is generally considered healthy. A lower DSCR may limit the credit amount or result in a denial.
Comparison of Funding Options
The table below summarizes the typical maximum funding amounts for different types of business financing. These ranges are based on general market standards and may vary by lender and borrower profile.
| Financing Type | Typical Maximum Limit | Primary Collateral | Approval Speed |
|---|---|---|---|
| Asset-Based Line of Credit | $1,000,000 to $50,000,000 | Accounts Receivable, Inventory | 1 to 2 Weeks |
Each option has its own strengths and weaknesses. SBA lines offer the highest limits and potentially lower costs, but they take longer to approve. Online lines are faster and more accessible, but they have lower limits and higher costs. Asset-based lines are ideal for businesses with significant assets, but they require collateral. Traditional bank lines are a good middle ground for established businesses with strong financials.
Key Takeaways
- The maximum funding amount for a business line of credit varies widely by lender and program type.
- Asset-based lines can extend into the millions for businesses with significant assets.
- Credit score, time in business, and revenue are the primary approval factors.
- Creative Capital Solutions connects businesses with third-party funding providers.
- Approval is subject to underwriting and is not guaranteed.
- Businesses should consult with a broker to find the right fit for their specific needs.
Frequently Asked Questions
What is the highest business line of credit I can get?
Does Creative Capital Solutions lend money directly?
No, Creative Capital Solutions is a broker. We connect businesses with third-party funding providers. We do not lend money directly. All funding is subject to underwriting and approval by the funding provider.
How long does it take to get a business line of credit?
Online lenders can provide funding in as little as 2 to 3 business days. SBA loans can take 2 to 6 weeks. Asset-based loans may take 1 to 2 weeks. The timeline depends on the lender and the complexity of the application.
What credit score do I need for a business line of credit?
Most online lenders require a personal credit score of at least 650 to 700. Some lenders consider lower scores, especially if the business has strong revenue. A higher credit score can result in a higher credit limit and better terms.
Can I get a business line of credit with bad credit?
Yes, some lenders consider bad credit or lower credit scores. However, approval is not guaranteed. Lenders will also look at other factors, such as revenue and time in business. Creative Capital Solutions can help you find funding providers that consider credit as one of many factors.
What is the difference between a line of credit and a term loan?
A line of credit is a revolving facility that allows you to borrow, repay, and borrow again. A term loan is a lump sum that is repaid over a fixed period. Lines of credit are more flexible, while term loans are better for large, one-time purchases.
How does Creative Capital Solutions help businesses?
Creative Capital Solutions helps businesses by connecting them with third-party funding providers. We evaluate your business and provide an overview of available options. We help you navigate the application process and find the right fit for your needs.