
Creative Capital Solutions is a commercial financing broker that connects businesses with third-party funding providers. It is not a direct lender. This guide evaluates its reputation for rapid decisions, details its alternative financing products, and explains the high-cost terms associated with certain funding types. We cover entity verification, product structures, and cost implications to help you make an informed decision.
Entity Verification and Corporate Structure
Understanding the legal structure of a financial service provider is the first step in assessing its reputation. Creative Capital Solutions operates as a Doing Business As (DBA) of Siena Marketing and Consulting, Inc. This corporate structure is critical for transparency. A DBA allows a company to operate under a name different from its registered legal entity. In this case, Siena Marketing and Consulting, Inc. is the primary legal entity, while Creative Capital Solutions is the trade name used for its commercial financing brokerage services.
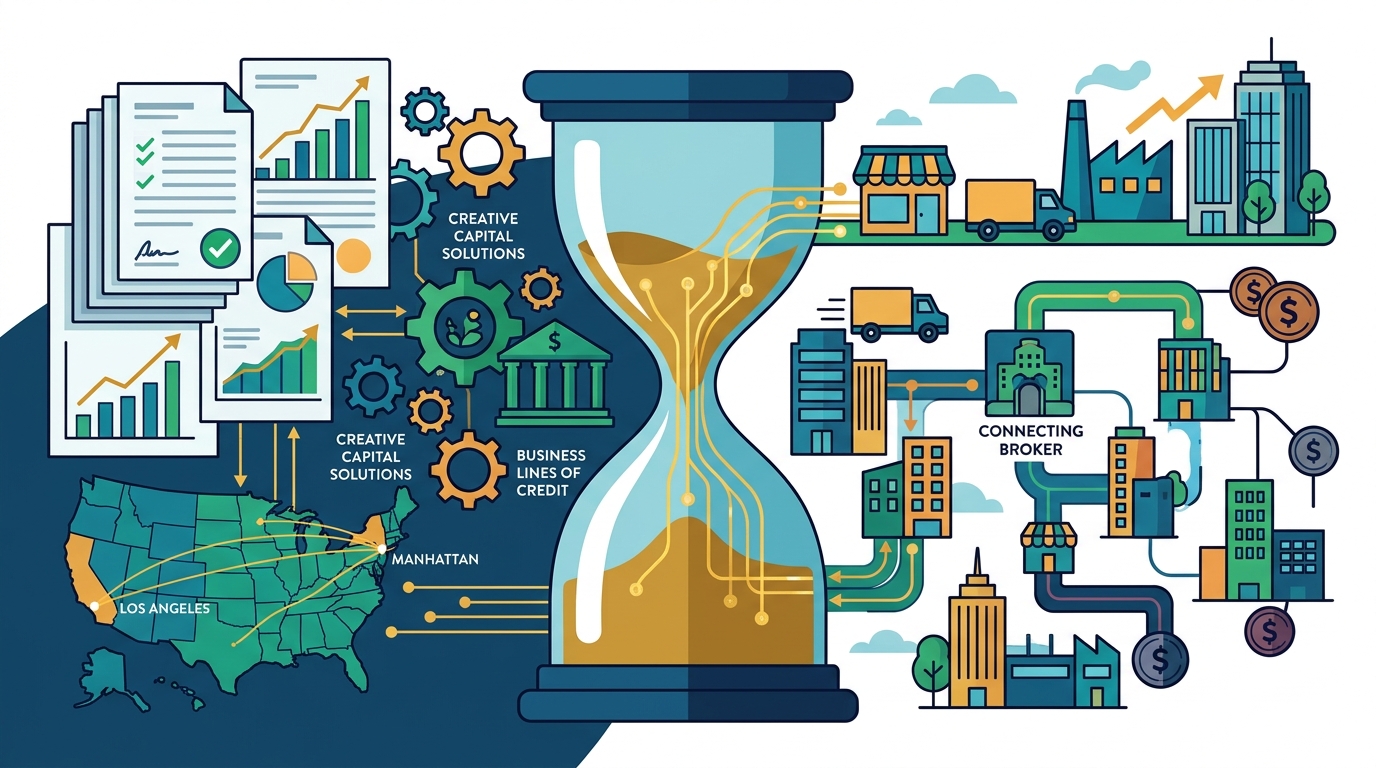
It is essential to distinguish between a direct lender and a broker. A direct lender provides funds from its own balance sheet. A broker, like Creative Capital Solutions, acts as an intermediary. It matches businesses with third-party funding providers. This distinction impacts how you evaluate the company. You are not borrowing from Creative Capital Solutions directly. You are entering into an agreement with a funding provider that Creative Capital Solutions has sourced for you. This model allows for a wider variety of funding options but requires careful review of the final contract terms.
Regulatory and Operational Transparency
Commercial financing brokers operate under specific state regulations. States such as New York, California, and Texas have disclosure requirements for commercial financing. Creative Capital Solutions is headquartered in Manhattan, New York, with operations in Los Angeles, California. These locations are subject to strict commercial financing disclosure laws. The company provides a privacy policy that outlines how personal and business data is handled. This policy is accessible on their website and is a standard component of any reputable financial service provider.
When verifying the entity, you should look for clear contact information and a physical address. Creative Capital Solutions lists its address as 74 Broad St, Manhattan, New York 10004. This physical presence adds a layer of accountability. You can also verify the business registration through state corporate databases. In New York, you can search the Department of State records for Siena Marketing and Consulting, Inc. This step confirms that the entity is active and in good standing. It is a basic but important due diligence step for any business owner considering third-party financing.
The Brokerage Model Explained
The brokerage model in commercial financing involves several steps. First, the business applies with the broker. The broker collects financial documents, including tax returns, bank statements, and profit and loss statements. Next, the broker analyzes the business profile and matches it with suitable funding providers. Finally, the funding provider makes the final underwriting decision. Creative Capital Solutions states that their capital formation experts evaluate the business and typically provide a decision in minutes. However, this initial decision is not a final approval. The final approval rests with the third-party funding provider.
This multi-step process can sometimes lead to confusion. Business owners may think they are approved by Creative Capital Solutions, but they are actually approved by the lender. It is crucial to read the final contract carefully. The contract will name the actual funding provider. You should verify the reputation of that specific provider as well. Creative Capital Solutions serves as the point of contact for the application process, but the funding provider is the entity that holds the debt or receivable purchase agreement.
Alternative Financing Products
Creative Capital Solutions offers a range of financing products designed to address different business needs. These products include working capital advances, business lines of credit, and asset-based loans. Each product has a distinct structure, term length, and use case. Understanding these differences is key to selecting the right funding solution for your business.
Working Capital Advances
A working capital advance is a type of funding where the provider purchases a portion of your future receivables. It is not a loan. The provider gives you a lump sum of cash in exchange for a fixed percentage of your daily sales. Repayment continues until the total amount due is paid off. Creative Capital Solutions offers working capital advances ranging from $10,000 to $5,000,000. The terms typically range from 3 to 36 months. Funding can be received in as little as 48 hours. This speed makes it an attractive option for businesses with urgent cash flow needs.
Working capital advances are often used to cover operational expenses, such as payroll, inventory, or rent. They are particularly useful for businesses with seasonal revenue fluctuations. Because repayment is tied to sales, the burden of repayment decreases when sales are slow. However, this structure can result in higher overall costs compared to traditional loans. You must carefully evaluate the total cost of the advance before signing.
Business Lines of Credit
A business line of credit is a type of small business loan that provides funding to draw from whenever you are in need of capital. Unlike a lump-sum loan, a line of credit allows you to access a certain amount of money, pay it back, and borrow again. Creative Capital Solutions offers business lines of credit ranging from $10,000 to $250,000. The terms range from 6 to 36 months. Funding is typically available in 2 to 3 business days. This product is ideal for managing cash flow gaps, buying inventory, or addressing emergencies.
Asset-Based Loans
The loan-to-value (LTV) ratio is a key metric in asset-based lending. For equipment, the LTV is typically 50% with terms of 1 to 10 years. For real estate, the LTV is 75-80% with terms of 5 to 30 years. For inventory, the LTV is 50% with terms of 1 to 10 years. For accounts receivable, the LTV can be up to 85% for receivables under 90 days. These ratios determine how much you can borrow against your assets. You will need to provide business tax returns, financial statements, and debt schedules to apply for an asset-based loan.
High Cost Terms and Fee Structures
One of the most critical aspects of evaluating a financing provider is understanding the cost of the funds. Alternative financing products, such as working capital advances, often come with higher costs than traditional bank loans. These costs are not always expressed as an Annual Percentage Rate (APR). Instead, they may be expressed as a factor rate or a fixed fee. Understanding these terms is essential to avoid unexpected financial burdens.
Factor Rates vs. APR
Hidden Fees and Prepayment Penalties
In addition to the factor rate or interest rate, there may be other fees associated with the funding. These can include origination fees, processing fees, and late payment fees. You should ask about many potential fees before signing the contract. Some working capital advances have prepayment penalties. This means you may have to pay a fee if you pay off the advance early. Other advances allow prepayment without penalty. You should clarify this in the contract. Prepayment penalties can significantly increase the total cost if you plan to pay off the funding early.
It is also important to understand the repayment schedule. Working capital advances are typically repaid through daily or weekly deductions from your bank account. This automatic deduction can impact your cash flow. You should ensure that your business has enough cash flow to cover the deductions without disrupting operations. If your sales drop, the repayment amount may also drop, but the total amount due remains the same. This structure can be risky for businesses with volatile revenue. You should model different sales scenarios to ensure you can meet the repayment obligations.
Comparison of Financing Products
| Product Type | Amount Range | Term Length | Funding Speed | Collateral Requirement | Cost Structure |
|---|---|---|---|---|---|
| Working Capital Advance | $10,000 - $5,000,000 | 3 - 36 Months | 48 Hours | None (Receivables Purchase) | Factor Rate |
| Business Line of Credit | $10,000 - $250,000 | 6 - 36 Months | 2 - 3 Business Days | Personal Guarantee | Interest Rate (APR) |
| Asset-Based Loan | $1,000,000 - $50,000,000 | 1 - 30 Years | Quote in 1 Week | Equipment, Real Estate, Inventory, AR | Interest Rate (APR) |
Key Takeaways
- Creative Capital Solutions is a commercial financing broker, not a direct lender. It connects businesses with third-party funding providers.
- The company operates as a DBA of Siena Marketing and Consulting, Inc., with headquarters in Manhattan, New York.
- Working capital advances are purchases of future receivables, not loans. They are repaid through a percentage of daily sales.
- Business lines of credit are loans that allow you to draw, repay, and redraw funds. They are suitable for cash flow management.
- Asset-based loans require collateral such as equipment, real estate, or inventory. They are suitable for larger funding needs.
- Factor rates on working capital advances can be significantly higher than traditional loan APRs. Always convert the factor rate to an APR for comparison.
- Funding decisions are made by third-party providers, not Creative Capital Solutions. Final approval is subject to underwriting.
- Always review the final contract carefully to understand the total cost, fees, and repayment terms before signing.
Frequently Asked Questions
Is Creative Capital Solutions a direct lender?
No, Creative Capital Solutions is a commercial financing broker. It does not lend money directly. It connects businesses with third-party funding providers. The final funding agreement is between your business and the funding provider.
How fast can I get funding from Creative Capital Solutions?
Funding speed varies by product. Working capital advances can be funded in as little as 48 hours. Business lines of credit are typically funded in 2 to 3 business days. Asset-based loans may take longer, with quotes provided within one week.
What is a working capital advance?
A working capital advance is a funding product where the provider purchases a portion of your future receivables. It is not a loan. You receive a lump sum of cash in exchange for a fixed percentage of your daily sales.
Do I need good credit to qualify for funding?
Credit is not the only factor in the underwriting process. Businesses with less-than-perfect credit may still qualify for funding. The provider will consider your revenue, time in business, and other financial factors. Approval is not guaranteed.
What are the costs associated with a working capital advance?
Working capital advances are typically priced using a factor rate. This is a multiplier applied to the principal amount. The total cost can be higher than a traditional loan. You should ask for the APR equivalent to compare costs accurately.
Can I prepay my working capital advance?
Prepayment terms vary by funding provider. Some advances allow prepayment without penalty, while others may have prepayment penalties. You should clarify the prepayment terms in the contract before signing.
What documents do I need to apply for an asset-based loan?
You will need to provide business tax returns, business financial statements, profit and loss statements, balance sheets, accounts receivable and accounts payable reports, and a business debt schedule.
Is Creative Capital Solutions affiliated with the SBA?
No, Creative Capital Solutions is not affiliated with the Small Business Administration (SBA). It is a private commercial financing broker. It offers alternative financing products, not SBA loans.
Conclusion
Creative Capital Solutions provides a streamlined process for businesses seeking rapid funding decisions. As a commercial financing broker, it connects you with third-party providers offering working capital advances, lines of credit, and asset-based loans. The speed of funding is a significant advantage, but it comes with the need for careful cost analysis. You must understand the difference between a factor rate and an APR. You should also verify the reputation of the specific funding provider named in your contract.
Before applying, review your financial documents and determine your exact funding needs. Compare the terms of the offer with other financing options. Ensure that the repayment structure aligns with your cash flow. Creative Capital Solutions can be a helpful resource for navigating the commercial financing landscape. However, you are responsible for making the final decision. To start your application, you can apply online or contact our team directly. Always read the fine print and consult with your financial advisor before entering into any financing agreement.