
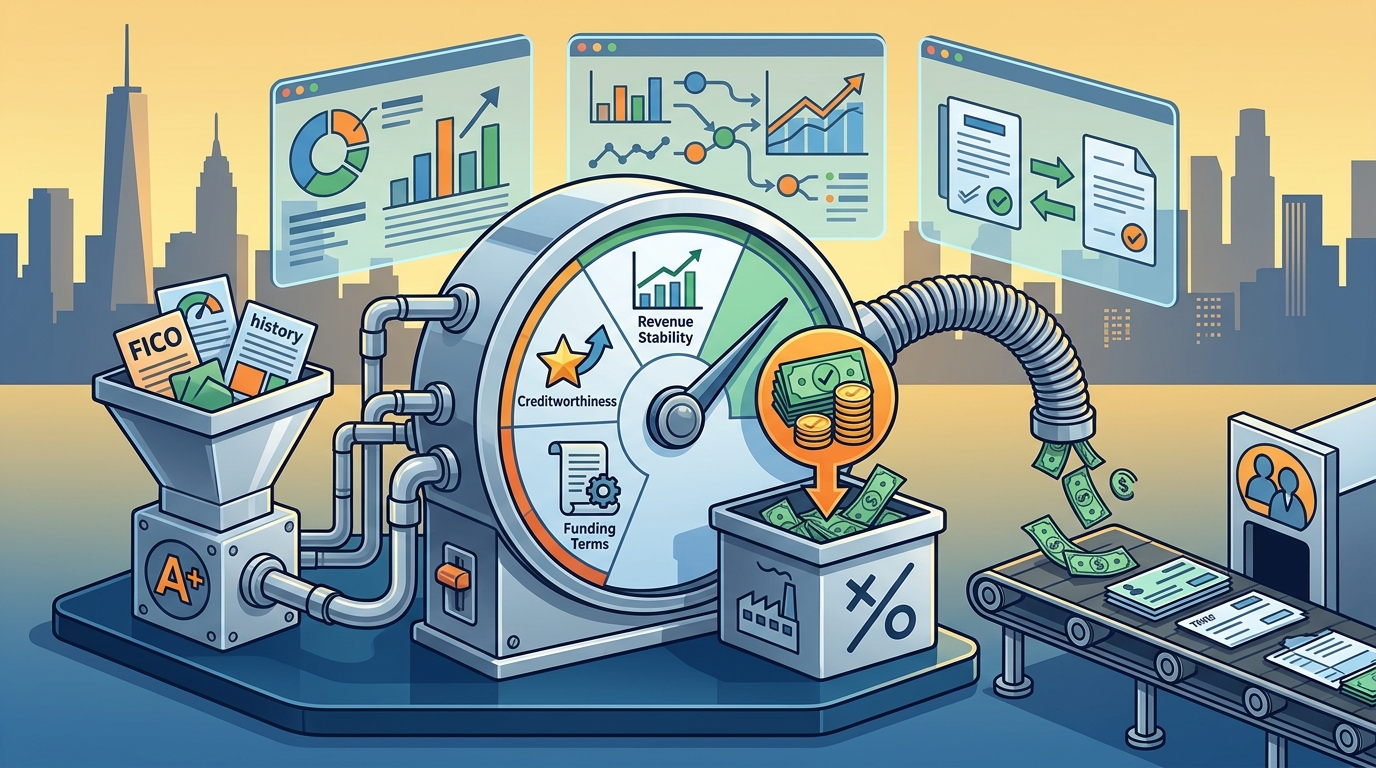
The cost of a business line of credit for payroll is primarily driven by your creditworthiness, revenue stability, and the specific terms of the funding agreement. Creative Capital Solutions helps business owners understand these variables to secure competitive pricing. By analyzing key financial metrics, you can predict how much you will pay to cover payroll obligations efficiently.
How Credit Scores Influence Pricing
The Role of Credit History
Revenue Stability and Cash Flow Analysis
Business revenue stability is a critical determinant of funding costs. Lenders analyze your bank statements to assess cash flow consistency. Businesses with steady, predictable revenue often qualify for better terms. Creative Capital Solutions evaluates your financial health to ensure you are matched with a provider that values your cash flow patterns.
Seasonal Fluctuations
Many businesses experience seasonal revenue spikes and dips. Lenders account for these fluctuations when pricing your line of credit. If your revenue is highly seasonal, you may face different pricing structures compared to businesses with flat revenue. Understanding your seasonal patterns helps in negotiating better terms.
Business Age and Industry Risk
The age of your business and your industry sector significantly impact funding costs. Newer businesses often face higher costs due to limited operating history. Certain industries are considered higher risk, which can increase pricing. Creative Capital Solutions considers these factors to find providers who understand your specific industry dynamics.
Industry Specifics
Industries like construction or hospitality may have different risk profiles than technology or manufacturing. Lenders adjust their pricing based on these industry-specific risks. Knowing how your industry is perceived helps you anticipate potential cost variations. according to Risk management Wikipedia
Loan Term and Draw Frequency
The length of your repayment term and how frequently you draw funds affect the total cost. Longer terms may have lower monthly payments but higher total interest costs. Frequent draws and repayments can sometimes lead to different fee structures. Creative Capital Solutions helps you model these scenarios to find the most cost-effective approach for your payroll needs.
Term Length Considerations
Shorter terms often come with higher monthly payments but lower total interest. Longer terms spread the cost over time but may increase the total amount paid. Choosing the right term length is crucial for managing your overall financing costs.
Collateral and Security Requirements
Secured lines of credit, which require collateral, often have lower costs than unsecured options. Providing assets like equipment or real estate can reduce the lender's risk. This reduced risk translates to better pricing for you. Creative Capital Solutions can help you understand the trade-offs between secured and unsecured funding options.
Types of Collateral
Different types of collateral carry different risk levels for lenders. Equipment, inventory, and real estate are common forms of collateral. The value and liquidity of your collateral can influence the final cost of your line of credit.
Key Takeaways
- Credit scores are the primary driver of interest rates and fees.
- Stable revenue and consistent cash flow lead to better pricing.
- Business age and industry risk profiles affect lender risk assessment.
- Term length and draw frequency impact total financing costs.
- Secured lines of credit often cost less than unsecured options.
- Working with a broker like Creative Capital Solutions helps navigate these factors.
Frequently Asked Questions
What is the main factor affecting the cost of a business line of credit?
The main factor is your creditworthiness, which includes your credit score and payment history. Lenders use this to determine the risk level and price your funding accordingly.
Does business age affect the cost of funding?
Yes, newer businesses often face higher costs due to limited operating history. Lenders may charge more to compensate for the increased risk associated with younger companies.
How does revenue stability impact pricing?
Stable, predictable revenue generally leads to lower costs. Lenders prefer businesses with consistent cash flow, which reduces their risk and allows for more competitive pricing.
Can I lower the cost of my line of credit by providing collateral?
Yes, secured lines of credit often have lower costs than unsecured options. Providing collateral reduces the lender's risk, which can translate to better terms for you.
Does the industry I operate in affect my funding costs?
Yes, certain industries are considered higher risk, which can increase pricing. Lenders adjust their rates based on the specific risks associated with your industry.
How does Creative Capital Solutions help with funding costs?
Is there a guaranteed rate for business lines of credit?
No, rates vary based on individual business profiles and market conditions. There is no guaranteed rate, as pricing depends on multiple factors including credit, revenue, and industry.
Next Steps for Your Payroll Funding
Understanding these factors empowers you to make informed decisions about your payroll financing. Creative Capital Solutions is here to guide you through the process, ensuring you find the right funding solution for your business needs. To explore your options, apply for funding or for a personalized consultation.