
A draw feature allows a business to borrow only the specific amount of capital needed at a given time, rather than receiving a full lump sum. This mechanism provides flexibility by letting companies access funds as they arise, paying interest only on the drawn amount. Creative Capital Solutions helps businesses navigate these flexible financing options to ensure they have the right capital structure for their operational needs.
Understanding the Core Mechanics of a Draw
A business line of credit is a type of small business loan that provides funding to draw from whenever you are in need of capital. Unlike a term loan, which disburses a fixed amount upfront, a line of credit functions as a revolving pool of money. When a business initiates a draw, it requests a specific portion of its available credit limit. This request triggers a transfer of funds to the business's bank account. The remaining credit limit stays available for future use. This structure is ideal for managing variable cash flow needs without incurring unnecessary debt.
The Role of Credit Limits and Availability
The Process of Initiating a Draw Request
Initiating a draw is typically a straightforward process that can be completed online or through a funding representative. The business owner logs into their account and specifies the amount they wish to draw. They must ensure the requested amount does not exceed their available credit limit. Once the request is submitted, the funding provider reviews the request to ensure it complies with the terms of the agreement. In many cases, the funds are transferred to the business's bank account within one to two business days. This speed allows businesses to respond quickly to opportunities or emergencies.
Documentation and Verification
While the initial application for a line of credit involves a detailed financial review, subsequent draws often require less documentation. However, some providers may request proof of the intended use of funds, such as an invoice for inventory or a contract for equipment. This verification step helps ensure the funds are used for legitimate business purposes. It also helps the provider monitor the health of the business's cash flow. Creative Capital Solutions guides clients through these requirements to ensure a smooth draw process.
Repayment Structures and Interest Accrual
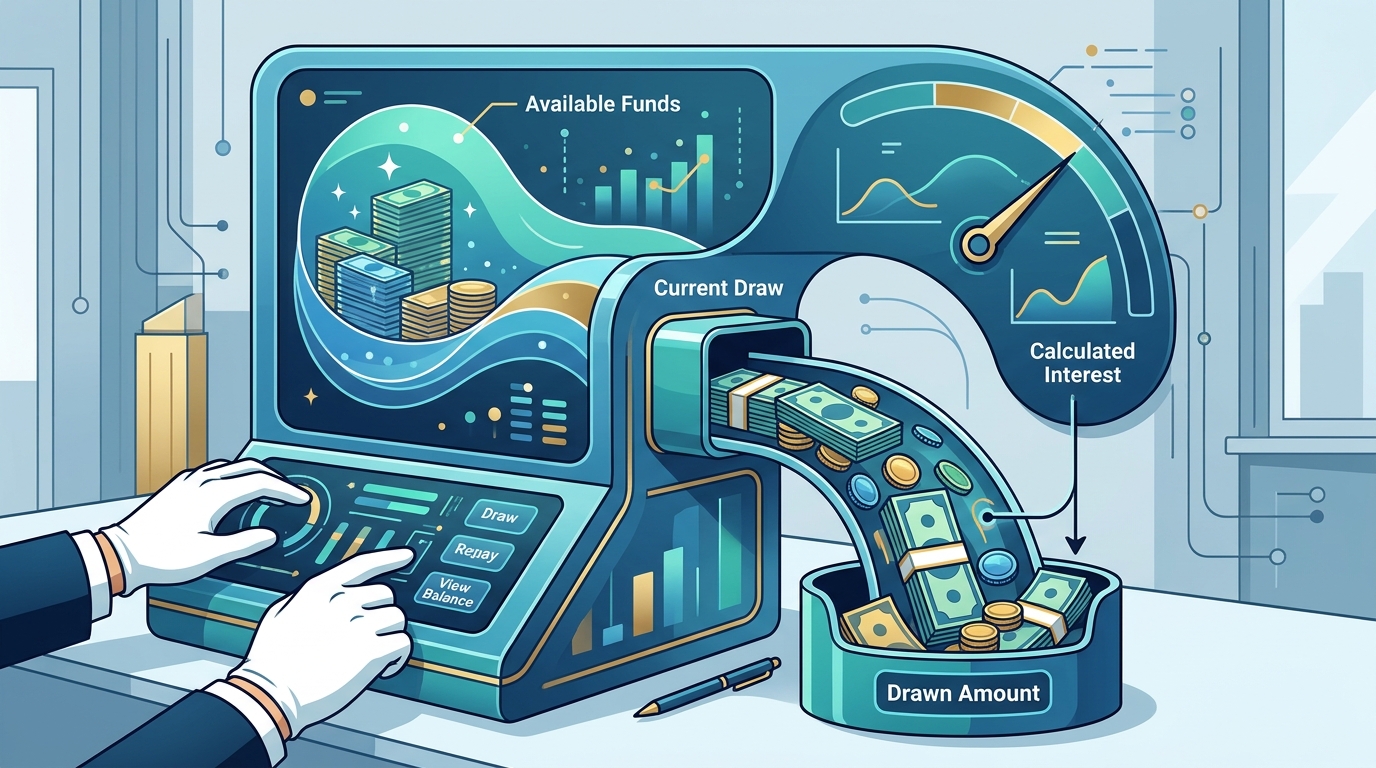
Interest on a line of credit accrues only on the amount that has been drawn, not on the total credit limit. This is a significant advantage over term loans, where interest accrues on the full principal amount from day one. Businesses can choose between different repayment structures, such as interest-only payments or amortizing payments. Interest-only payments allow the business to pay just the interest each month, keeping the principal balance unchanged. This can be useful during seasonal peaks when cash flow is tight. Amortizing payments, on the other hand, gradually pay down the principal over time.
Minimum Payment Requirements
Most line of credit agreements require a minimum monthly payment. This payment usually covers the accrued interest and a small portion of the principal. Failing to make the minimum payment can result in late fees or a negative impact on the business's credit score. It is crucial for business owners to understand their repayment schedule and ensure they have sufficient cash flow to meet these obligations. Creative Capital Solutions works with businesses to structure repayment terms that align with their revenue cycles.
Strategic Uses for Drawn Funds
The flexibility of the draw feature makes it suitable for a variety of business needs. Common uses include covering payroll during slow months, purchasing inventory for seasonal demand, or managing unexpected expenses. Because the funds are available on demand, businesses can use them as a safety net for emergencies. They can also use them to seize growth opportunities, such as hiring new staff or expanding marketing efforts. The key is to use the draw feature strategically, ensuring that the borrowed funds generate a return that exceeds the cost of borrowing.
Managing Cash Flow Gaps
Many businesses experience cash flow gaps due to the timing of their receivables and payables. A line of credit can bridge these gaps by providing immediate liquidity. For instance, a business might receive a large order but need to pay suppliers before the customer pays. A draw allows the business to cover the supplier costs immediately, maintaining good relationships with vendors. Once the customer pays, the business can repay the draw, restoring its available credit. This cycle helps maintain operational stability without the stress of long-term debt.
Key Takeaways
- A draw feature allows businesses to borrow only the amount needed, preserving the rest of their credit limit.
- Interest accrues only on the drawn amount, making it a cost-effective solution for variable funding needs.
- Draw requests are typically processed quickly, often within one to two business days.
- Businesses can choose between interest-only and amortizing repayment structures to fit their cash flow.
- Strategic use of draws can help manage cash flow gaps and seize growth opportunities.
- Creative Capital Solutions assists businesses in selecting the right line of credit terms for their specific needs.
Frequently Asked Questions
How quickly can I access funds from a line of credit?
Once a draw request is approved, funds are typically transferred to your bank account within one to two business days. The exact timing depends on the funding provider and the specific terms of your agreement.
Do I have to pay interest on the full credit limit?
No, you only pay interest on the amount you have actually drawn. The unused portion of your credit limit does not accrue interest, which can save you money compared to a term loan.
Can I draw multiple times from the same line of credit?
Yes, as long as you have available credit, you can draw multiple times. As you repay the funds, they become available for drawing again, allowing you to reuse the facility throughout the term.
What happens if I miss a minimum payment?
Missing a minimum payment can result in late fees and may negatively impact your business credit score. It is important to maintain a repayment schedule that aligns with your cash flow to avoid these penalties.
How does Creative Capital Solutions help with line of credit draws?
Creative Capital Solutions helps businesses select the right line of credit products and guides them through the application and draw process. We ensure that the terms and repayment structures align with your business goals and cash flow needs.
Conclusion
Understanding the draw feature is essential for businesses looking to leverage a line of credit effectively. By borrowing only what is needed and repaying strategically, companies can maintain financial flexibility and stability. Creative Capital Solutions is committed to helping businesses access the right financing solutions to support their growth and operational needs. To explore your options, apply for business funding today and see how a line of credit can work for your business.